

Till: Debit Card for Kids
4.5

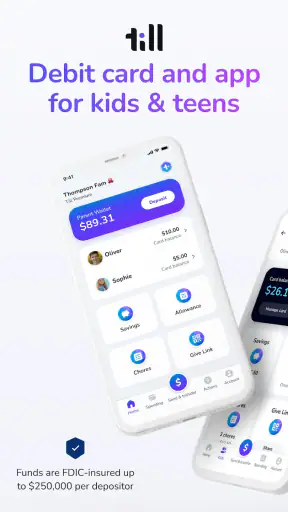
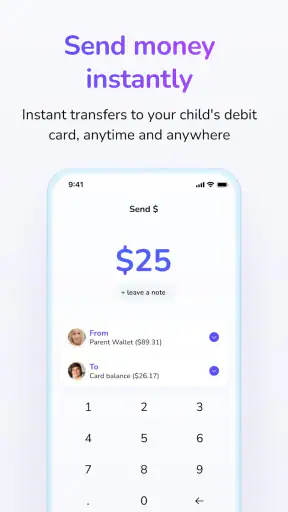
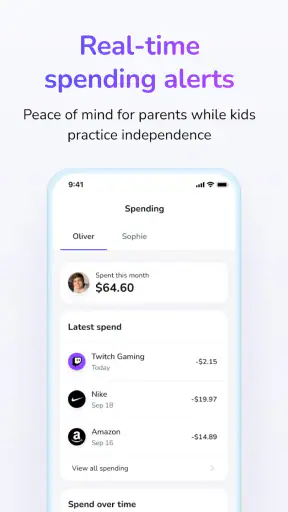
I approached Till: Debit Card for Kids as a parent would: not just asking whether the first setup feels appealing, but whether the app can support useful money habits after the novelty wears off. Developed by Till Financial, this free finance app pairs a debit card with a mobile experience aimed at helping children and teenagers become more thoughtful spenders. Its audience rating is Everyone, and that broad label makes sense for a family-focused money tool, although the real suitability depends on the child’s age, independence, and the amount of guidance an adult is ready to provide.
My first impression is that Till is more interesting as a routine-building tool than as a simple way to hand a child spending money. A conventional cash allowance is easy to give but difficult to track. A standard bank account may be too adult-oriented for a young user. Till sits between those options, giving families a more visible way to discuss spending while keeping the experience centered on a debit card. That difference matters because the lasting value of a financial app is rarely the card itself; it is whether the family actually uses the conversations and habits around it.
From an appealing first week to a useful monthly routine
Why the first week feels approachable
The first-week appeal comes from turning an abstract lesson into something a child can understand immediately. A card is tangible, and purchases create natural moments to talk about choices. Instead of explaining budgeting only with examples on paper, a parent can discuss a real purchase soon after it happens. That makes the learning process more concrete without requiring a child to manage a full adult banking relationship.
I also like the separation between the parent’s oversight and the child’s spending experience. A young person can begin practicing independence, while the adult remains involved enough to provide boundaries and context. That balance is more useful than either extreme: giving unrestricted access too early or keeping every money decision completely controlled. The app works best when the card becomes a starting point for short, calm conversations rather than a replacement for them.
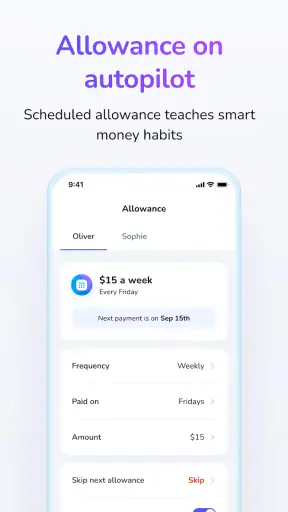
For a family beginning with a regular allowance, the practical workflow is straightforward in principle. The adult establishes the arrangement, the child uses the card for appropriate purchases, and both sides can use the resulting activity to discuss priorities. The important tip is to decide the rules before the first purchase. Agree on what the card is meant to cover, which requests require a conversation, and how mistakes will be handled. Without that agreement, the app can become a source of arguments instead of a teaching aid.
The product has also reached a meaningful audience, with over 100 thousand installs and a 4.5 average from around 2.2 thousand ratings. Those figures suggest that the concept is resonating with families, but they should not be treated as proof that every household will enjoy the same experience. A finance tool depends heavily on family habits. A parent who checks in regularly may find it valuable, while someone hoping for a completely hands-off allowance system may quickly lose interest.
The first real test is not the download
The first week is where many family finance products feel more useful than they eventually become. Setup creates a sense of progress, the child is curious about the card, and the parent is motivated to explain how it works. The more revealing test arrives after the first few ordinary purchases. If the app helps both sides understand where money went and what to do next, it has a chance to become part of the household routine. If it only attracts attention when something goes wrong, its role will be much smaller.
One realistic example would be a teenager buying a snack after school and later wanting a more expensive item. Rather than simply saying yes or no, a parent can use the earlier purchase as the basis for a discussion about trade-offs. The child is not just being told to save; they can think about whether the smaller purchase was worth delaying the larger goal. That kind of repeated decision is where Till can offer more educational value than handing over cash with no record.
There is a useful trade-off here. Visibility can encourage better decisions, but it can also make every small purchase feel monitored. I would introduce the app as a shared learning tool, not as a surveillance device. Children are more likely to engage honestly when they understand that the purpose is to build judgment, not to criticize every choice. The parent’s tone may matter as much as the app’s interface.
What creates value after the excitement fades
Month-to-month value depends on repetition. The app is strongest when it supports a predictable allowance rhythm and gives the family a reason to review spending occasionally. A short weekly check-in can be enough: look at recent purchases, identify one decision the child feels good about, and discuss one adjustment for the next period. This is more sustainable than turning every transaction into a formal lesson.
For younger children, the adult may need to lead most of the review. For teenagers, the better approach is to ask questions and let them explain their choices. That gradual shift in responsibility is one of the most promising aspects of a child-focused debit card. The same tool can support different levels of independence, provided the parent changes the conversation as the child grows.
A less obvious strength is that the card can make irregular spending easier to discuss than a fixed cash handout. A child may not notice how several small purchases affect a limited amount of money when using cash casually. Seeing those decisions together can reveal patterns: spending immediately after receiving money, forgetting about small purchases, or saving successfully for something specific. The insight is not that every purchase must be optimized. It is that patterns become easier to notice when the family has a shared reference point.
I would not rely on Till alone to teach financial literacy. It can create useful situations, but it does not remove the need to explain needs versus wants, delayed gratification, privacy, and what to do when a purchase goes wrong. Parents should also talk about keeping card details private and asking for help with unfamiliar transactions. The app can support those lessons, but the family still supplies the judgment.
Where the usual alternatives may be better
Compared with cash, Till offers greater visibility and a more modern experience, but cash can be better for a very young child who is still learning physical counting. Compared with adding a child to an ordinary bank account, Till is more clearly focused on supervised independence and family discussion. A conventional account may be preferable for an older teenager who needs broader banking capabilities or is preparing for adult financial responsibilities.
There is also a simple alternative: a spreadsheet, envelope system, or regular family allowance conversation. Those methods cost less in complexity and may be enough for a family that already communicates well about money. Till earns its place when the card and app make the routine easier to follow, not merely because a digital product feels more sophisticated.
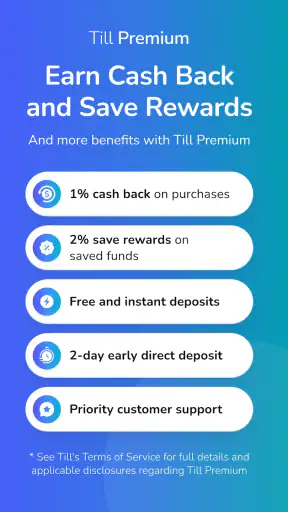
The app is free to download, but in-app purchases range from around eight dollars to around 79 dollars per item. That makes it important to understand the ongoing cost of the arrangement before treating it as a permanent household system. A free entry point is helpful for trying the concept, yet families should judge recurring value against their actual use rather than assuming that the initial download is the whole financial commitment.
The maintenance burden parents should expect
No child debit card is truly set-and-forget. The adult still needs to keep the allowance arrangement consistent, review activity often enough to notice problems, and update expectations as the child’s needs change. If the parent stops participating, the app may become little more than a payment card. That is not necessarily a flaw, but it does mean the product’s educational promise requires maintenance.
The most effective maintenance routine is deliberately small. I would choose one regular review time, keep the discussion brief, and focus on decisions rather than interrogating every transaction. A monthly review can cover whether the amount still makes sense, whether the child is saving toward anything, and whether the card is being used for the purpose the family agreed on. If a child is spending independently, a shorter check-in more often may work better than a long conversation at the end of the month.
Another practical tip is to separate allowance discussions from discipline whenever possible. If the card becomes the main punishment mechanism, the child may learn to see money management as a source of anxiety rather than independence. Consequences may sometimes be necessary, but the everyday routine should leave room for mistakes and reflection. That is how the app can remain useful beyond its novelty period.
Parents should also consider how much supervision is appropriate. A child who is ready to make small decisions may still need help recognizing suspicious activity, understanding a declined purchase, or deciding when to ask before spending. A teenager may resent excessive involvement, while a younger child may need very clear boundaries. Till cannot solve that developmental difference automatically, so the adult has to adjust the level of oversight.
Sources of fatigue and friction
The biggest source of fatigue is the need for consistency. If money arrives unpredictably, rules change from one week to the next, or the parent rarely checks in, the app loses much of its teaching power. The child may still have a card, but the family no longer has a clear system. That is a household-management problem rather than a technical one, yet it directly affects whether the product feels worthwhile.
Another possible frustration is the tension between independence and control. Parents may want detailed awareness of spending, while children may interpret that awareness as a lack of trust. I would address this by defining the boundaries openly: explain what the adult will review, what the child may decide alone, and which purchases need prior discussion. Clear expectations are less tiring than renegotiating the rules after every disagreement.
Cost can become a separate fatigue point. Since the app includes in-app purchases, families should think beyond the attraction of a free download. If the household uses the service only occasionally, a basic cash system could be more sensible. If the card becomes part of a steady allowance routine and the guidance is genuinely helpful, the expense may feel easier to justify. The right answer depends on use, not on the presence of a finance label.
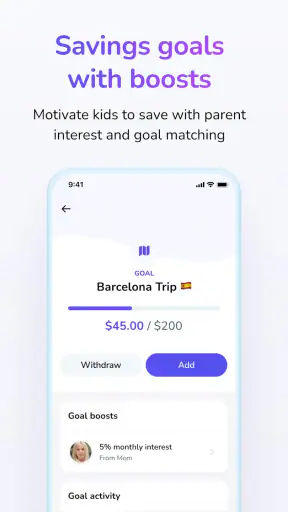
There is also a risk of over-focusing on transactions. A child can learn to watch a balance without learning why saving matters or how to plan for irregular expenses. I would pair the app with simple goals: saving for a particular item, reserving money for a planned outing, or keeping a small cushion for unexpected needs. Those goals make the numbers meaningful and prevent the experience from becoming a constant exercise in checking.
Families should skip Till if they want a fully independent banking product for an older user, if they are unwilling to participate in regular conversations, or if a child is not ready to manage a debit card responsibly. It may also be unnecessary for parents who already have a reliable allowance method and do not need a dedicated app. In those situations, a conventional account or a simple manual system may be clearer and less demanding.
How the app holds up over the long term
Till is maintained by Till Financial, and its current version is 162.41.0. It runs on Android 7.0 and later, which makes it accessible on many older Android devices. Those details are useful for families sharing or reusing a phone, although device compatibility is only one part of a smooth experience. The more important question is whether the parent and child can keep the arrangement understandable as circumstances change.
After the first month, I would judge the app by three practical questions. Does the child make more deliberate choices? Does the parent spend less time manually tracking allowance money? And do conversations become easier rather than more frequent and tense? If the answer is yes to at least two of those questions, the app is doing something meaningful. If not, the card may be adding administration without improving the family’s habits.
The long-term value is strongest for families that want a gradual bridge between cash allowance and adult banking. It gives children a chance to practice decisions while an adult remains involved. It is less compelling as a badge of independence or as a substitute for teaching. The product earns lasting space when it is used to create a repeatable routine, not when it is treated as a one-time financial lesson.
My overall view is positive but measured. I like the way Till turns everyday spending into material for practical conversations, and I think its focus on children and teenagers makes it more approachable than many ordinary banking alternatives. At the same time, the app asks parents to provide structure, patience, and ongoing attention. That requirement is easy to overlook during the exciting first week.
For a family ready to share responsibility gradually, the free app is worth exploring, especially when the goal is to build spending awareness rather than simply distribute money. For a household seeking zero maintenance, a completely unrestricted card, or a full adult banking replacement, I would look elsewhere. The lasting benefit comes from the habit around the card, not the card alone. Used that way, Till can remain useful well after the initial novelty fades.
4.5
318.00 Reviews
Pros
- Parents can set spending limits and monitor transactions in real time.
- Kids learn budgeting through practical
- supervised everyday spending.
- The debit card works at many stores and online merchants.
- Parents can quickly lock or unlock the card from the app.
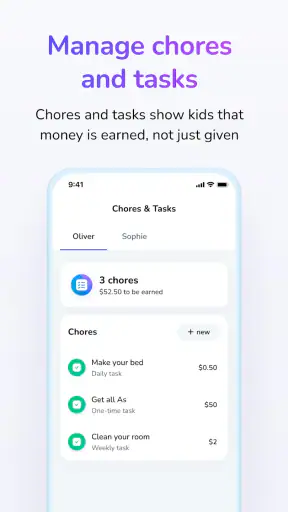
- Allowance and chore features can encourage regular saving habits.
Cons
- Some features may require a paid subscription or additional fees.
- Availability and card features can vary by country or region.
- Younger children may still need guidance to use the app safely.
- Internet access is needed to check activity and manage card settings.
- Not all merchants may accept the card for certain transactions.


